Strategic Sale to Global Fire Protection Group
Valuation-led Transaction Advisory Resulting in a Successful Strategic Acquisition
| Transaction Overview | |
|---|---|
| Industry | Fire Protection Services |
| Location | Central Queensland, Australia |
| Transaction Type | Share Sale |
| Buyer | Strategic Acquirer |
| Enterprise Value | Confidential |
| EBITDA Mutliple Achieved | ~6.5x Historical EBITDA |
| Deal Structure | All-cash transaction |
| Workforce | ~60 employees |
| Revenue Profile | 70%+ recurring inspection, testing & maintenance revenues |
| Key Outcome | Deal multiple materially exceeded initial broker assessments |

Client Overview
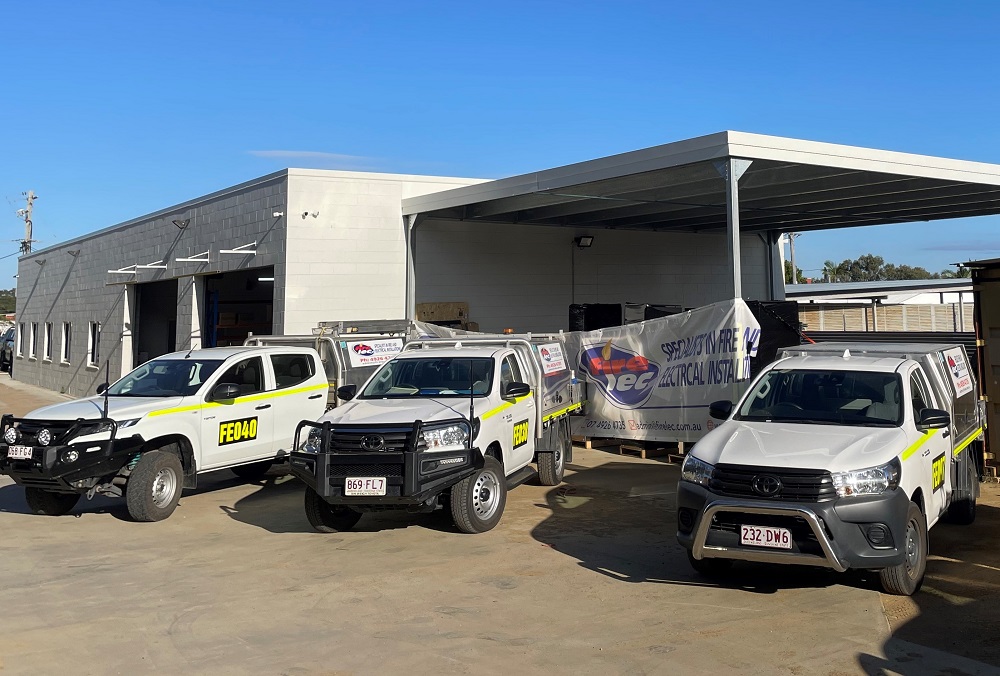
Firelec was a leading regional fire protection services provider headquartered in Central Queensland, delivering inspection, testing, maintenance and installation services to a diversified customer base across commercial and industrial sectors. The business had established a strong reputation within the region, underpinned by long-term customer relationships, recurring contracted revenues and a highly skilled workforce.
At the time of engagement, Firelec employed approximately 60 staff and was generating annual revenues of approaching $15 million, with historical growth exceeding 20% per annum. EBITDA margins consistently exceeded 25%, reflecting the strength of the operating model and the high proportion of recurring service revenues.
The business was ultimately acquired by a subsidiary of API Group Corporation through its Australian platform Chubb Fire & Security Australia.
Initial Engagement
BSP Strategic was initially introduced to Firelec by the founders’ long-standing accountant following several unsolicited approaches from business brokers. Initial broker assessments had suggested a valuation of approximately 3.5x EBITDA. However, the referring accountant recognised that the business possessed characteristics more commonly associated with premium strategic acquisitions — particularly its recurring revenue profile, contracted customer base and strong operating margins.
BSP Strategic was engaged to undertake an independent Calculation of Value assessment to establish a supportable fair market value range and identify the underlying value drivers of the business.
Following detailed analysis, BSP determined a fair market value equivalent to approximately 5.0x EBITDA on a standalone basis, excluding any premium attributable to strategic acquirers or special purchasers. The valuation findings provided the founders with significantly greater clarity regarding the market positioning of the business and ultimately led to the decision to formally explore an exit process.
Valuation Methodology
The valuation was prepared using a market-based approach, with Comparable Transactions adopted as the primary methodology. The analysis was supported by transaction evidence sourced from recognised global M&A databases including PitchBook and S&P Capital IQ.
The valuation was further cross-checked against comparable publicly traded businesses operating within the fire protection and facility services sectors.
Given the substantial volume of fire protection service transactions completed globally in recent years — particularly across the United States and Australia — there was sufficient market evidence to confidently assess fair market value and benchmark achievable transaction multiples.
Strategic Assessment & Sale Readiness Review
Following the valuation, BSP Strategic undertook a comprehensive Sale Fitness Review designed to identify transaction risks, operational gaps and opportunities to enhance value prior to market engagement.
The review included analysis of:
- Financial reporting integrity
- Revenue composition and recurring income streams
- Customer contracts and change-of-control risks
- Related party arrangements
- Property and lease structures
- Licensing and regulatory compliance
- Systems, workflows and operational controls
- Employee structure and key personnel dependencies
- Shareholder alignment and transaction objectives
- Insurance, asset registers and governance documentation
Several key transaction risks and complexities were identified:
- Financial reporting did not separately classify revenue streams, limiting visibility over recurring versus project-based income.
- A share sale structure was considered preferable due to the complexity of transferring large volumes of customer relationships and rolling service arrangements.
- Several key customer contracts contained change-of-control provisions requiring consent.
- The business operated in a highly constrained regional labour market, increasing retention risk for skilled technicians.
- Four directors had differing commercial objectives, ages and tax outcomes.
- Two younger directors were considered critical to post-transaction continuity and QBCC licensing transition requirements.
Strategic Value Drivers
BSP identified several characteristics that materially increased the attractiveness of the business to strategic acquirers:
- A highly scaled and skilled assembled workforce across technicians, sprinkler fitters, electrical services and management.
- Long-term recurring revenues under multi-year service and maintenance contracts with Tier-One customers.
- Strong EBITDA margins relative to industry peers.
- Automated operational workflows supporting scalable service delivery.
- Legislated and mandated inspection and maintenance activities generating highly defensive recurring revenues.
- Historical growth exceeding 20% per annum with a strong forward pipeline of work.
These attributes positioned Firelec as a strategically valuable acquisition target for larger national and international fire protection groups seeking regional expansion, workforce capability and contracted revenue streams.
Value Improvement & Risk Mitigation
Prior to commencing the sale process, BSP implemented a structured risk mitigation and value enhancement program tailored to the proposed transaction.
Key initiatives included:
- Comprehensive revenue analysis to isolate and validate recurring revenue streams and historical growth trends.
- Preparation of detailed supporting schedules and source documentation to substantiate revenue quality.
- Independent market appraisals for related-party properties utilised by the business.
- Documentation and formalisation of internal systems, policies and operational procedures.
- Reconciliation of plant and equipment to fixed asset registers and financial statements.
- Establishment of a fully populated and highly secure electronic data room prior to market engagement.
This work materially improved buyer confidence and enabled BSP to present a highly defensible investment thesis during negotiations and due diligence.
Buyer Engagement & Transaction Process
Following completion of the Sale Fitness Review, BSP Strategic was formally engaged to manage a confidential strategic sale process.
A targeted buyer universe was developed focused on:
- Global and national fire protection service providers
- Strategic acquirers seeking regional expansion
- Private equity groups with existing investments in the fire protection sector
Following execution of confidentiality agreements, selected parties were provided access to a detailed Information Memorandum through a secure data room with buyer activity analytics enabled.
The process generated substantial strategic interest, resulting in multiple management meetings, detailed Q&A processes and several Expressions of Interest.
A preferred acquirer was subsequently selected, with negotiations leading to a Non-Binding Indicative Offer within a range of approximately 5.5x to 6.5x EBITDA.
Extensive legal, financial and operational due diligence followed, involving advisors and executives from both Australia and the United States. Financial due diligence was undertaken by the Corporate Finance division of API Group, while operational due diligence was led locally by Chubb Fire & Security Australia.
The buyer’s strategic rationale was compelling. BSP understood that the acquirer had experienced local workforce constraints and operational capacity limitations within the region, making Firelec’s assembled workforce, customer base and regional footprint highly valuable from both a defensive and growth perspective.
Transaction Outcome
The transaction ultimately proceeded via a Share Purchase Agreement negotiated directly between BSP Strategic and senior executives of API Group in the United States. Negotiations included detailed comparative transaction analysis and financial modelling to support the proposed valuation parameters.
A final transaction multiple of approximately 6.5x historical EBITDA was agreed under an all-cash structure, inclusive of a retention amount of approximately 15% held for 24 months in relation to warranty obligations.
The original founders exited the business upon completion, while two younger directors remained with the business for a transitional integration period to support continuity of customer relationships, workforce stability and licensing requirements.
Key Takeaways
- An independent valuation established a materially higher fair market value range than initial broker assessments.
- Early identification and mitigation of transaction risks significantly strengthened buyer confidence.
- Detailed analysis of recurring revenue streams played a critical role in supporting valuation uplift.
- Strategic buyer targeting created competitive tension and improved negotiating leverage.
- The final transaction multiple achieved was nearly double the valuation initially suggested by national brokerage firms.